Today's Mortgage Rates, in Perspective:
Market Insight
Market Insight
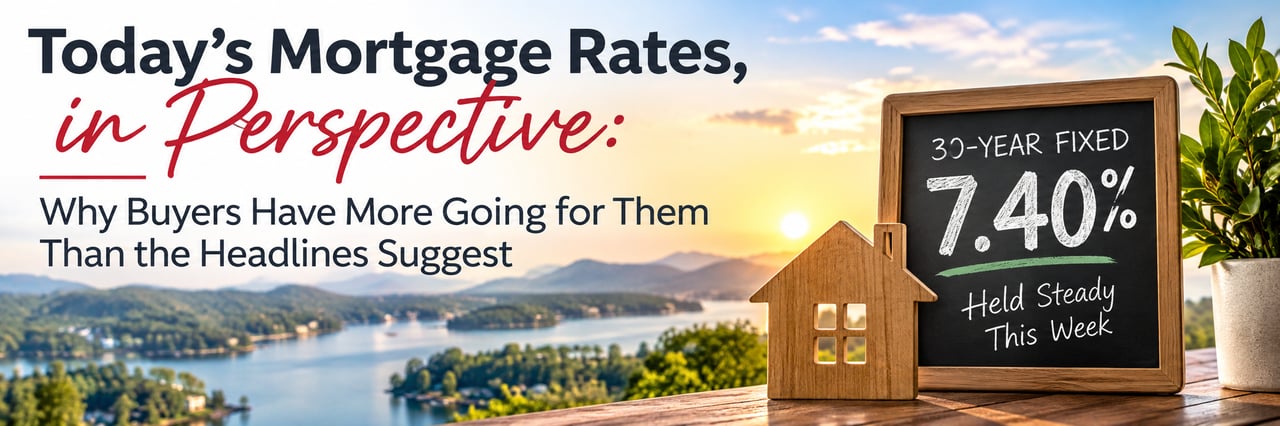
If you've glanced at the news lately, you've probably seen the headline: mortgage rates are back above 7%. As of Freddie Mac's October 15 survey, the average 30-year fixed rate sits at 7.40%.
The good news: rates held steady this week, pausing after several straight weeks of increases. Still, it's easy to read that number and decide to wait. But before you put your home search on hold, let's zoom out — because a single number without context can be misleading, and the bigger picture is a lot more encouraging than the headlines let on.
Most of us formed our sense of a "normal" mortgage rate between 2009 and 2021, when rates sat below 5% — and briefly dipped under 3%. Here's the thing: those years were the exception, not the rule. That stretch was shaped by a financial crisis, a pandemic, and extraordinary emergency action by the Federal Reserve.
Look at the longer history and today's rate looks a lot less scary:
Period | Average 30-Year Fixed Rate |
|---|---|
1972–2025 (50+ year average) | 7.70% |
1996–2000 (the late-'90s housing boom) | 7.57% |
2000 | 8.05% |
1981 (all-time annual high) | 16.63% |
Today (Oct. 15, 2026) | 7.40% |
Source: Freddie Mac Primary Mortgage Market Survey annual averages.
In other words, today's rate is actually a bit below the long-run average going back to the early 1970s, and right in line with the late 1990s — a period remembered as a great time to buy a home. Generations of homeowners bought, built equity and thrived at rates just like these.
Numbers on paper are one thing; your monthly budget is another. On a $250,000 loan, the principal-and-interest payment at today's 7.40% rate works out to roughly $1,731 a month. At the 2000 average of 8.05%, that same loan would have run about $1,843 — over $100 more every month.
Your actual rate and payment will depend on your credit, down payment, loan type and taxes and insurance, so a quick conversation with a trusted local lender is always the best next step.
1. More homes to choose from. After several years of very tight supply, inventory has been improving. Freddie Mac's chief economist noted this summer that more homes coming on the market and slower price growth are giving buyers better options and helping create a more balanced market. More choices mean you're less likely to settle.
2. Less competition and more room to negotiate. When rates tick up, some buyers sit on the sidelines. That's your opportunity. Fewer bidding wars mean more room to negotiate on price, ask for repairs, or request seller help with closing costs — some buyers even use seller concessions to buy down their interest rate.
3. You can refinance a rate — you can't go back and buy at yesterday's price. You may have heard the saying, "Marry the house, date the rate." If rates come down in the future, refinancing may be an option to lower your payment (lender approval and closing costs apply). But the home you love — and the price you negotiate today — is yours to keep. Waiting for a lower rate can also mean waiting for more competition to return when it drops.
Rates are higher than they were a few years ago — no question. But measured against the last 30 and 50 years, today's market is far closer to "normal" than the headlines suggest. And with more inventory and less competition, buyers who are ready have real advantages right now.
The right time to buy isn't about timing the market perfectly. It's about finding the right home, at a payment that fits your life.
Whether you're buying your first home, moving up, or looking for a place on the lake, I'd love to help you run the numbers and connect you with a trusted local lender.
Rates cited are national averages from Freddie Mac's Primary Mortgage Market Survey for conventional loans with 20% down and excellent credit, and are for informational purposes only. They are not a quote or offer of credit. Your rate will vary.
Market Insight
Market Insight
When you work with Jeff Kennedy and his team, you benefit from professionals who understand your needs and will work their absolute hardest to ensure excellent results for you and your family. Give Jeff a call today and discover the difference he can make for you!